Market Events
Housing, work, health, essential bills, technology, windfalls and cooperation. An ordinary day can change the price of staying on the board.
50 of 50 cards remaining
Tap a logo to inspect it. Pick a deck to draw a card.
Fictional satire. Game currency.
Real-world connections are sourced in the exhibit.
An illustrative playing field. Positions and scale are conceptual.
Trace financial power ↓Explore the ownership ↓The Power of Refusal
Boycotts, ownership, and economic agency.
The labels change. The money often ends up in the same place. Learn the ownership—and decide what deserves your support.

Play the exhibition / 100 cards
Terms and conditions apply. Opportunity sold separately.
Draw a scenario, read the fine print, and ask who gains, who pays and who gets to change the rules. Choose the market’s terms or the government’s policy deck.
Fictional satire. These cards describe invented game scenarios, not actual companies, laws or universal financial practices. Amounts are game currency. Effects are a creative prototype that has not been playtested or balanced.
Housing, work, health, essential bills, technology, windfalls and cooperation. An ordinary day can change the price of staying on the board.
50 of 50 cards remaining
Taxes, lobbying, public assets, collective action, accountability and reform. The rules can move money just as effectively as the dice.
50 of 50 cards remaining
Search the printed messages and effects, or filter by deck, outcome and theme.
The catalog’s 28 notes define a starting point for tabletop play. This exhibit draws and displays cards. Resolve payments, choices, timers and shared funds using the rules you select for your game.
Card text from the supplied American_Dream_100_Card_Catalog.xlsx: Market Events and Government & Policy, cards M01–M50 and P01–P50. Prototype notes from Start Here. Adapted/new labels are the catalog’s own draft categories.
A system governed by wealth cannot deliver meaningful rule by the people. Finance, inherited fortunes, and corporate power shape the choices placed before us. A ballot alone cannot dismantle the economic dependencies that sustain that power.
Strategic boycotts need to begin. They require education, coordination, persistence, and practical alternatives. Learn the ownership. Choose a demand. Move money and attention together.
Power organized around wealth. Financial resources can purchase access, fund advocacy, and sustain influence across election cycles.
Power concentrated among a small group. The question is how open decision-making remains to people outside that group.
A critical term for corporate dominance over public decision-making. Trace ownership, lobbying, contracting, and regulation to test the claim.
Plutocracy supplies the wealth. Oligarchy concentrates the decisions. Corporatocracy embeds those interests in the institutions of daily life. This is the political critique that drives the exhibition: formal choice loses substance when economic power repeatedly determines the available choices.
Technical and professional gatekeepers can become another concentration of authority. The demand is for transparent decisions, independent scrutiny, and meaningful routes of appeal. Expertise carries public responsibilities; credentials should never make power unaccountable.
Gilens and Page analyzed 1,779 U.S. policy cases from 1981–2002. Their model found substantial independent influence from economic elites and business-oriented groups, with little or no independent influence from average citizens. The study provides a historical measure of unequal responsiveness in federal policymaking.
Read the 2014 study ↗Stop sustaining what you want to change. Build what you want to sustain.
Start with the named parent, subsidiaries, and completed transactions. Then identify who holds voting rights and who appoints decision-makers.
Look for the contract, platform, distributor, formulary, license, or procurement rule that a participant cannot easily avoid.
A manufacturer, retailer, employer, regulator, or public purchaser may hold a different lever. Address the demand to someone with actual authority.
Define a published policy change, a contract revision, or another independently checkable outcome. A slogan can unite people; evidence tells them whether anything changed.
The founders died. The fortunes, institutions, and methods of concentrating power outlived them. Companies split, merged, and changed names. Family capital moved through inheritances, banking houses, and endowed institutions. Today’s ownership map has a history—and that history is still being written.
Consolidation concentrates decisions as well as assets. A trust can place separate companies under common direction. A merger can absorb a competitor. A banking network can connect industrial firms through credit, shareholdings, and overlapping boards. The records below show how those arrangements took shape and how their legacies continued.
Rothschild & Co traces its business records to Mayer Amschel Rothschild in 1769. His five sons established businesses in Frankfurt, London, Paris, Vienna, and Naples, building a network active in government bonds and international finance. Family partnerships could connect capital across borders long before today’s multinational banks.
John D. Rockefeller and his associates formed Standard Oil in 1870. In 1882, its trust centralized control over component businesses in nine trustees. They selected company directors and officers and determined distributions of consolidated profits. Separate corporate names could sit beneath one center of decision-making.
National Archives: how the trust worked ↗ · Company origins ↗
On February 8, 1895, the U.S. Treasury contracted with a syndicate linking J. P. Morgan & Co., August Belmont & Co., and N. M. Rothschild & Sons to replenish its gold reserve. The agreement exchanged U.S. bonds for 3.5 million ounces of standard gold coin, with at least half supplied from Europe.
The signed contract makes a structural dependency visible: a public institution turned to a private financial network for emergency resources.
J. P. Morgan helped bring Carnegie Steel and other steel businesses together into U.S. Steel in 1901. The banker’s role extended into the organization of production itself: financial deals combined previously separate industrial enterprises under a single corporate structure.
Oil trusts and steel mergers used different legal arrangements to pursue a common advantage—greater scale and fewer independent centers of competition.
During the Panic of 1907, Morgan organized private financing to stabilize the banking system. In 1910, bankers and officials met secretly at Jekyll Island to develop a monetary reform proposal. The resulting Aldrich plan faced opposition for giving bankers too much control.
The Federal Reserve Act, signed in 1913, emerged from that political struggle. It combined regional Reserve Banks with a federally appointed oversight board. Banking influence, government authority, and public accountability were contested in the design of the institution itself.
The Carnegie Foundation published the Flexner Report in 1910. Rockefeller-funded organizations then used grants to advance laboratory- and hospital-based medical education. The Rockefeller Foundation, incorporated in 1913, received $100 million from John D. Rockefeller in its first year.
Endowments gave private wealth a durable role in setting research and training priorities. The medical reforms strengthened scientific education while contributing to an exclusionary institutional landscape; historical scholarship documents unequal support for Black medical schools.
Original Flexner Report ↗ · Medical education grants ↗ · Foundation history ↗ · Historical analysis of exclusion ↗
The count records overlapping board positions within the report’s specified network. It measures institutional connections; present-day control requires present-day ownership and voting records.
The Supreme Court ordered Standard Oil’s dissolution in 1911. Successor businesses continued, acquired assets, adopted new names, and sometimes combined again. This selected branch follows that corporate history into the present.
The breakup produced 34 companies, including Jersey Standard, Socony, and Vacuum Oil.
Socony-Vacuum’s lineage led to Mobil. Jersey Standard became Exxon in 1972.
The companies merged on November 30, 1999. Two branches of the old Standard Oil structure reunited.
ExxonMobil completed its acquisition of Pioneer Natural Resources on May 3, 2024.
1911 Supreme Court opinion ↗ · Successor-company history ↗ · Pioneer acquisition closing ↗
The Sherman Act of 1890 created a federal basis for challenging monopolistic practices. The Clayton and Federal Trade Commission Acts followed in 1914. In the 1999 Exxon–Mobil case, the FTC required divestitures or assignments involving about 2,431 gas stations, alongside other assets, to settle its competition concerns.
Consolidation and public intervention have developed together. Merger terms, enforcement decisions, court remedies, and the resources devoted to oversight help determine whether competition survives.
David Rockefeller became president of Chase Manhattan in 1961 and chair and CEO in 1969, serving until his retirement in 1981. He also chaired the Rockefeller Institute for Medical Research, later Rockefeller University, from 1950 to 1975. One career connected banking leadership and biomedical philanthropy.
The Rockefeller Brothers Fund, established in 1940, received a $250 million bequest from his estate in 2018. Its trustee directory lists Justin Rockefeller and Valerie Rockefeller as of this exhibition’s October 8, 2026 review. Inheritance, endowment, and board service carry the family’s institutional presence across generations.
David Rockefeller’s institutional roles ↗ · Fund and bequest history ↗ · Trustee directory ↗
J. P. Morgan’s firm became a public company in 1940 and merged with Chase Manhattan in 2000. JPMorganChase traces its organization to more than 1,200 predecessor institutions. The corporate name carries a long history of accumulated businesses.
Rothschild & Co provides a documented example of continuing family control. Its French and British businesses combined in 2003; it delisted from the Paris stock exchange in 2023. The group describes itself as family-controlled, with a seventh generation of family leadership. Corporate succession and continuing family control are distinct relationships that can each be traced.
JPMorganChase: predecessors and mergers ↗ · Rothschild & Co: structure and history ↗
The industrial age did not invent dynastic power. Long before Standard Oil, European families accumulated land, financed rulers, arranged strategic marriages, and passed property and privilege to their heirs. A fortune could change form across generations: commercial profits became estates, estates supported social rank, and family relationships opened doors to political office.
Read alongside the Rothschild and Rockefeller histories above, these cases widen the frame. Wealth can survive its founder through deliberate arrangements for inheritance and institutional continuity. Each family has its own branches, alliances, rivalries, and reversals; the connections become meaningful when we identify the people, assets, institutions, and dates.
The Orsini were a major Roman aristocratic family whose branches held estates and supplied military leaders, cardinals, and popes. Their long rivalry with the Colonna also shows that aristocratic interests could conflict.
UCLA holds Orsini papers spanning the fourteenth through twentieth centuries. Property inventories, marriage settlements, dowries, wills, and inheritance records make the transmission of wealth traceable through specific transactions. They also document relationships with foreign states and the papal court.
The Medici banking dynasty rose to dominate Florence, produced popes, and became hereditary rulers. Alessandro became the first Duke of Florence in 1532; Cosimo I succeeded in 1537. Patronage and portraiture helped project the authority of the ruling family.
This history also has a boundary: Medici grand-ducal rule ended when Gian Gastone died without an heir in 1737. Its political dynasty ended while its buildings and collections remained an institutional legacy.
The Met: Medici politics and rule ↗ · Uffizi: the succession of 1737 ↗
The Colonna connect centuries of Roman landholding with church and political office. Oddone Colonna became Pope Martin V in 1417; the family palace served as his papal seat from 1420 to 1431.
The palace history records a family entail established in 1800 to preserve its art collections together. Such arrangements show one concrete way a family could protect accumulated assets for future generations. The palace remains a family residence as well as a place where part of that patrimony is publicly exhibited.
For a ruling house, marriage could create claims to entire territories. Maximilian’s marriage to Mary of Burgundy in 1477 and his son Philip’s marriage to Joanna of Castile and Aragon in 1496 helped connect dynastic inheritances across Europe.
The 1515 marriage agreements with the Jagiellonian dynasty established further inheritance claims in Bohemia and Hungary. War, succession disputes, and diplomacy shaped the outcomes. Here, kinship was an explicit instrument of government.
The Augsburg Fuggers connected mining and metals trading with loans to European rulers. Their history records financing for royal courts and military campaigns, followed by investments in landed estates.
In 1548, Anton Fugger restricted succession to male descendants to preserve wealth and property, while providing endowments and dowries for daughters. The firm was dissolved in 1658; family estates and foundations carried other forms of continuity beyond the original business.
The Torlonia demonstrate how an aristocracy could absorb a rising financial family. From modest French origins, Giovanni Torlonia advanced through banking and the purchase of large estates. He and his son Alessandro became bankers to the papacy.
In 1809, Pius VII enrolled Giovanni and his descendants in Rome’s nobility. Matrimonial strategies and property accumulation helped consolidate the family’s position. Status could be acquired, then handed down.
Clarice Orsini’s marriage to Lorenzo de’ Medici joined a Florentine banking family to Roman aristocratic and papal connections. Their 1468 agreement specified a dowry of 6,000 Roman florins in money and valuables; celebrations followed in Florence in 1469. The alliance offered military and political connections beyond Florence.
The Fugger family history records that Jakob Fugger lent approximately two-thirds of the money used to secure the electors’ votes for Charles V. This is a specific financial connection to the selection of a ruler.
The papal decision to admit Giovanni Torlonia and his descendants to Roman nobility converted an acquired social position into recognized hereditary status. Banking, land, and formal privilege met in a documented act.
In the Roman context, the term refers to aristocratic allegiance to the papacy after the loss of papal temporal rule in 1870. A 1929 account distinguishes older feudal houses such as the Orsini and Colonna from families elevated through a papal relative, including the Borghese, Barberini, Chigi, and Odescalchi, and from the Torlonia’s financial route into nobility.
These are different histories of status, patronage, and inheritance. A shared label alone does not establish a single organization or a common chain of command.
A surname is a starting point. To establish who controls an asset or institution today, follow ownership shares, voting rights, trustees, appointment powers, and the dates when those relationships changed. A loan, a marriage, a board seat, and ownership each describe a different connection.
The World Bank and UNODC’s Stolen Asset Recovery Initiative documents how shell companies, trusts, and foundations have been misused to conceal the beneficiaries of corruption. Structures spanning several countries can make ownership difficult to trace. Those documented cases do not implicate every user of these structures or every family discussed here.
The histories above support a record of inherited advantage and, in specific periods, direct political rule. Claims that particular families own a modern government, direct population-control policies, or enjoy legal immunity require evidence of the relevant decisions, powers, and conduct. Genealogy alone cannot establish them.
Historical expansion: sources reviewed October 2026. Archival collections, museum histories, economic research, and family institutional histories are linked beside the claims they support.
Monetary power also depends on the rules governing currency, reserves, and international payments. These changes occurred across several administrations and decades.
Roosevelt’s gold program restricted private monetary gold holdings. The Gold Reserve Act of 1934 transferred monetary gold to the Treasury and prohibited domestic dollar redemption in gold.
Gold Reserve Act history ↗Delegates from 44 countries agreed on a new international monetary framework and institutions that became the IMF and World Bank. The resulting system linked currencies to the dollar, with official dollar-to-gold convertibility at $35 an ounce.
Bretton Woods history ↗On August 15, Nixon suspended the conversion of dollars into gold for foreign monetary authorities, ending the remaining official gold-convertibility commitment.
State Department: the Nixon shock ↗After further currency crises, major currencies moved to floating against the dollar. The Bretton Woods fixed-exchange-rate system gave way.
The 1971–1973 transition ↗Legal tender concerns currency’s legal status for settling debts. Gold convertibility concerns the ability to exchange currency for gold. The dollar retained legal-tender status after the gold window closed.
The Federal Reserve’s governance combines a federal Board of Governors with regional Reserve Banks. Member banks hold statutory Reserve Bank stock subject to legal restrictions; appointments, legislation, oversight, and monetary-policy decisions determine how its public authority is exercised.
Modern mergers and acquisitions keep reshaping markets. A 2022 Defense Department report described a contraction from 51 to five major aerospace and defense prime contractors since the 1990s. USDA research documents concentration in meat processing. These are sector-specific records of a recurring process: more economic activity passing through fewer large organizations.
Share of U.S. steer and heifer slaughter handled by the four largest firms in 2019.
USDA / 2023 report ↗Major aerospace and defense prime contractors, since the 1990s, as reported in 2022.
Defense Department ↗Predecessor institutions in JPMorganChase’s corporate history. A lineage count, rather than a market-share measure.
Corporate history ↗A monopoly involves one dominant supplier in a defined market; an oligopoly involves a small group. Concentration is measured within a product and geographic market. The atlas shows corporate families. Market-share studies measure how much of a defined market those families control; dated governance records identify who holds voting power.
Pfizer, Moderna and Bayer trade on public stock markets. Boehringer Ingelheim and Cargill are family-owned businesses. Syngenta Group is ultimately state-owned through Sinochem. Legal structure determines how ownership and control can be investigated.
Roche illustrates another distinction: a listed company can still have concentrated voting power. It reported a shareholder voting pool holding 64.97% of its issued voting shares at December 31, 2025. Roche also issues non-voting securities, separating economic interests from formal voting rights.
Roche share structure and dated voting pool ↗ · Company ownership sources below ↗
The exhibition’s argument is that accumulated private wealth can keep shaping public life long after its original owners are gone. The practical investigation follows specific powers: who holds the votes, allocates credit, awards grants, negotiates contracts, and sets the rules? Those connections identify where organized public pressure can reach a decision-maker.
Explore the present-day ownership atlas ↗The number printed on a banknote can stay the same while the amount it buys shrinks. Across decades, rising consumer prices erode a fixed cash balance. This is one part of the pressure on people whose pay, benefits or savings fail to keep pace.
An independent reconstruction of the long-run currency comparison, using World Bank consumer-price data sourced from the IMF. Each country starts at 100% in 1971. This measures domestic buying power, not exchange rates, gold prices or household wealth.
Choose a country and move through the annual observations. On small screens, swipe the chart horizontally to read its full timeline.
A fixed 100 USD held without interest buys about 12.91 USD worth of goods and services at 1971 prices in 2024. To preserve the original buying power, it would need to grow to 774.70 USD.
Shared endpoint: 2024 is the latest year available for all eight countries in this October 2026 World Bank snapshot. Lines connect annual observations; purchasing power can temporarily rise when prices fall.
A falling currency line tracks an unchanged amount of money. A household's purchasing power also depends on income, hours worked, taxes, benefits, debt and the prices it actually pays.
Inflation-adjusted income expresses income after allowing for rising prices. The Census series beside this text rises over the long run, with setbacks. It does not show a continuous decline for the typical U.S. household.
That leaves a sharper question for this exhibit: whose income and assets keep pace, whose essential costs rise fastest, and who has the power to protect their position?
BLS: income and purchasing power. Household income can include multiple earners; it is not an individual wage or a complete measure of living standards.
After inflation · annual estimates · 2025 dollars
Census CPS ASEC, all households. Pretax money income. Survey and processing changes affect comparability; dotted connections mark the 2013 redesign and 2017 processing change. The median does not describe every household or isolate housing affordability.
On August 15, 1971, Nixon suspended the dollar's conversion into gold for foreign monetary authorities. The decision helped end the Bretton Woods system. Inflation was already rising before that decision. Starting a chart here gives historical context; it does not establish a single cause for every country's subsequent inflation.
Federal Reserve History: the 1971 decision · Explore the exhibit's monetary timeline
Calculation: purchasing power retained (%) = 100 × CPI in 1971 ÷ CPI in the selected year. Loss = 100 minus the retained percentage. The cost of the equivalent 100-unit basket = 100 × selected-year CPI ÷ 1971 CPI. These calculations assume a fixed nominal balance earning no interest; they do not measure returns on savings accounts or investments.
CPI represents changing consumer prices. It is not a literal basket whose goods, quality and weights remain unchanged for five decades. Countries' baskets, geographic coverage and methods differ, so this compares each country's own price history rather than equal living standards or equal costs across countries. Housing purchase prices and financial assets are not interchangeable with consumer-price inflation.
Eight countries with complete 1971–2024 observations are shown; this is not an exhaustive currency ranking. All 432 CPI observations are published values in the source snapshot. No missing early years have been estimated. The supplied River graphic names IMF World Economic Outlook and World Bank data and says some early years were estimated; this reconstruction uses the World Bank's IMF International Financial Statistics CPI series instead. Different source vintages and endpoints can produce different percentages.
The income series uses Census's published 2025-dollar estimates, adjusted with C-CPI-U for 2000 onward and R-CPI-U-RS before 2000. It uses a different inflation-adjustment method from the currency chart. Where Census publishes two estimates for 2013 or 2017, the newer questionnaire or processing basis is used. Estimates have sampling uncertainty; the table below retains published margins of error. Other survey changes are documented in the original workbook.
Sources checked October 13, 2026. World Bank WDI, FP.CPI.TOTL; underlying source: IMF International Financial Statistics; snapshot updated 2026-10-08. Data · Definitions and coverage · BLS calculation method. World Bank data licensed CC BY 4.0; calculations and design by Nagy Design.
| Year | USD | CAD | GBP | CHF | JPY | AUD | INR | ZAR |
|---|---|---|---|---|---|---|---|---|
| 1971 | 100.00 | 100.00 | 100.00 | 100.00 | 100.00 | 100.00 | 100.00 | 100.00 |
| 1972 | 96.83 | 95.25 | 93.40 | 93.76 | 95.38 | 94.32 | 93.95 | 93.96 |
| 1973 | 91.20 | 88.61 | 85.53 | 86.21 | 85.46 | 86.46 | 80.34 | 85.86 |
| 1974 | 82.12 | 79.83 | 73.71 | 78.54 | 69.35 | 74.91 | 62.47 | 76.85 |
| 1975 | 75.24 | 72.14 | 59.34 | 73.61 | 62.07 | 65.05 | 59.08 | 67.76 |
| 1976 | 71.15 | 67.08 | 50.91 | 72.37 | 56.75 | 57.40 | 63.96 | 61.03 |
| 1977 | 66.81 | 62.12 | 43.95 | 71.44 | 52.47 | 51.11 | 59.05 | 54.91 |
| 1978 | 62.07 | 57.01 | 40.59 | 70.71 | 50.35 | 47.32 | 57.60 | 49.40 |
| 1979 | 55.79 | 52.23 | 35.79 | 68.22 | 48.55 | 43.36 | 54.20 | 43.61 |
| 1980 | 49.14 | 47.43 | 30.34 | 65.59 | 45.05 | 39.37 | 48.68 | 38.37 |
| 1981 | 44.53 | 42.17 | 27.12 | 61.59 | 42.94 | 35.96 | 43.03 | 33.29 |
| 1982 | 41.96 | 38.07 | 24.97 | 58.29 | 41.79 | 32.30 | 39.89 | 29.04 |
| 1983 | 40.65 | 35.96 | 23.87 | 56.62 | 41.01 | 29.35 | 35.65 | 25.86 |
| 1984 | 38.98 | 34.48 | 22.74 | 55.01 | 40.11 | 28.23 | 32.92 | 23.18 |
| 1985 | 37.64 | 33.16 | 21.44 | 53.18 | 39.31 | 26.45 | 31.18 | 19.94 |
| 1986 | 36.94 | 31.83 | 20.73 | 52.79 | 39.08 | 24.25 | 28.68 | 16.80 |
| 1987 | 35.64 | 30.50 | 19.90 | 52.04 | 39.03 | 22.35 | 26.36 | 14.46 |
| 1988 | 34.24 | 29.32 | 19.11 | 51.08 | 38.76 | 20.84 | 24.10 | 12.83 |
| 1989 | 32.66 | 27.93 | 18.07 | 49.52 | 37.90 | 19.38 | 22.51 | 11.18 |
| 1990 | 30.99 | 26.65 | 16.72 | 46.98 | 36.77 | 18.06 | 20.65 | 9.78 |
| 1991 | 29.73 | 25.23 | 15.56 | 44.38 | 35.61 | 17.50 | 18.14 | 8.48 |
| 1992 | 28.86 | 24.86 | 14.88 | 42.66 | 35.00 | 17.33 | 16.22 | 7.45 |
| 1993 | 28.03 | 24.41 | 14.51 | 41.30 | 34.57 | 17.03 | 15.26 | 6.79 |
| 1994 | 27.32 | 24.37 | 14.19 | 40.95 | 34.33 | 16.70 | 13.84 | 6.23 |
| 1995 | 26.57 | 23.85 | 13.82 | 40.22 | 34.37 | 15.96 | 12.56 | 5.73 |
| 1996 | 25.82 | 23.48 | 13.44 | 39.90 | 34.33 | 15.55 | 11.52 | 5.34 |
| 1997 | 25.23 | 23.11 | 13.15 | 39.69 | 33.74 | 15.52 | 10.75 | 4.92 |
| 1998 | 24.84 | 22.88 | 12.91 | 39.69 | 33.51 | 15.39 | 9.50 | 4.60 |
| 1999 | 24.31 | 22.49 | 12.69 | 39.37 | 33.63 | 15.16 | 9.07 | 4.37 |
| 2000 | 23.51 | 21.90 | 12.54 | 38.77 | 33.86 | 14.52 | 8.72 | 4.15 |
| 2001 | 22.87 | 21.36 | 12.35 | 38.39 | 34.11 | 13.90 | 8.40 | 3.93 |
| 2002 | 22.51 | 20.89 | 12.17 | 38.14 | 34.43 | 13.50 | 8.06 | 3.59 |
| 2003 | 22.01 | 20.32 | 12.00 | 37.90 | 34.52 | 13.14 | 7.76 | 3.39 |
| 2004 | 21.44 | 19.95 | 11.84 | 37.60 | 34.52 | 12.84 | 7.48 | 3.42 |
| 2005 | 20.73 | 19.52 | 11.59 | 37.16 | 34.62 | 12.50 | 7.18 | 3.35 |
| 2006 | 20.09 | 19.14 | 11.32 | 36.77 | 34.53 | 12.07 | 6.78 | 3.24 |
| 2007 | 19.53 | 18.74 | 11.05 | 36.50 | 34.51 | 11.80 | 6.38 | 3.05 |
| 2008 | 18.81 | 18.30 | 10.68 | 35.64 | 34.04 | 11.31 | 5.89 | 2.78 |
| 2009 | 18.87 | 18.25 | 10.47 | 35.81 | 34.51 | 11.11 | 5.31 | 2.59 |
| 2010 | 18.57 | 17.93 | 10.22 | 35.57 | 34.76 | 10.80 | 4.74 | 2.49 |
| 2011 | 18.00 | 17.42 | 9.84 | 35.48 | 34.86 | 10.45 | 4.35 | 2.37 |
| 2012 | 17.64 | 17.16 | 9.59 | 35.73 | 34.87 | 10.27 | 3.98 | 2.24 |
| 2013 | 17.38 | 17.00 | 9.38 | 35.81 | 34.75 | 10.02 | 3.61 | 2.12 |
| 2014 | 17.10 | 16.69 | 9.24 | 35.81 | 33.82 | 9.78 | 3.39 | 2.00 |
| 2015 | 17.08 | 16.50 | 9.21 | 36.23 | 33.55 | 9.64 | 3.23 | 1.91 |
| 2016 | 16.87 | 16.27 | 9.12 | 36.39 | 33.60 | 9.51 | 3.08 | 1.79 |
| 2017 | 16.52 | 16.01 | 8.89 | 36.19 | 33.44 | 9.33 | 2.98 | 1.70 |
| 2018 | 16.13 | 15.66 | 8.69 | 35.86 | 33.11 | 9.16 | 2.86 | 1.63 |
| 2019 | 15.84 | 15.36 | 8.54 | 35.73 | 32.95 | 9.01 | 2.76 | 1.57 |
| 2020 | 15.65 | 15.25 | 8.46 | 35.99 | 32.96 | 8.94 | 2.59 | 1.52 |
| 2021 | 14.94 | 14.75 | 8.25 | 35.78 | 33.04 | 8.69 | 2.46 | 1.45 |
| 2022 | 13.84 | 13.81 | 7.64 | 34.80 | 32.23 | 8.15 | 2.31 | 1.36 |
| 2023 | 13.29 | 13.29 | 7.16 | 34.07 | 31.21 | 7.72 | 2.19 | 1.28 |
| 2024 | 12.91 | 12.98 | 6.93 | 33.71 | 30.38 | 7.48 | 2.08 | 1.22 |
| Year | Median income | Margin of error (±) |
|---|---|---|
| 1971 | $59,970 | $382 |
| 1972 | $62,330 | $391 |
| 1973 | $63,680 | $399 |
| 1974 | $61,760 | $390 |
| 1975 | $60,080 | $402 |
| 1976 | $61,100 | $372 |
| 1977 | $61,400 | $380 |
| 1978 | $63,790 | $425 |
| 1979 | $63,670 | $496 |
| 1980 | $61,690 | $521 |
| 1981 | $60,650 | $523 |
| 1982 | $60,480 | $449 |
| 1983 | $60,100 | $450 |
| 1984 | $61,910 | $463 |
| 1985 | $63,090 | $562 |
| 1986 | $65,430 | $558 |
| 1987 | $66,250 | $514 |
| 1988 | $66,740 | $536 |
| 1989 | $67,880 | $614 |
| 1990 | $67,050 | $564 |
| 1991 | $65,100 | $515 |
| 1992 | $64,560 | $503 |
| 1993 | $64,240 | $494 |
| 1994 | $64,930 | $487 |
| 1995 | $66,990 | $637 |
| 1996 | $67,980 | $564 |
| 1997 | $69,390 | $527 |
| 1998 | $71,930 | $700 |
| 1999 | $73,760 | $566 |
| 2000 | $73,560 | $380 |
| 2001 | $72,350 | $364 |
| 2002 | $71,770 | $387 |
| 2003 | $71,810 | $513 |
| 2004 | $71,700 | $521 |
| 2005 | $72,810 | $401 |
| 2006 | $73,620 | $520 |
| 2007 | $74,810 | $343 |
| 2008 | $72,260 | $324 |
| 2009 | $71,790 | $505 |
| 2010 | $70,110 | $761 |
| 2011 | $69,070 | $570 |
| 2012 | $69,070 | $465 |
| 2013 | $71,670 | $1,439 |
| 2014 | $70,760 | $850 |
| 2015 | $74,590 | $697 |
| 2016 | $77,230 | $938 |
| 2017 | $78,600 | $680 |
| 2018 | $79,620 | $871 |
| 2019 | $85,320 | $1,123 |
| 2020 | $83,590 | $1,082 |
| 2021 | $83,270 | $712 |
| 2022 | $81,460 | $1,057 |
| 2023 | $84,730 | $667 |
| 2024 | $85,210 | $1,069 |
Industrial chemistry built enormous corporate portfolios. IG Farben’s formation and breakup, followed by later mergers and acquisitions, left a history that can be traced through named businesses and dated transactions.
Bayer, BASF, Hoechst, Agfa, Griesheim-Elektron, and Weiler-ter Meer.
A vast German chemical conglomerate spanning dyes, pharmaceuticals, industrial chemicals, synthetic materials, and crop protection.
Bayer reestablished in 1951. BASF reestablished in 1952. These were among the businesses created from the former conglomerate.
Bayer’s historical record ↗ · BASF’s historical record ↗
Founded as Monsanto Chemical Works.
Bayer completed its acquisition of Monsanto in June 2018, bringing a major seed and crop-protection business into the group.
Inspect Bayer’s portfolio ↗Archival Monsanto pamphlet ↗ · Completed acquisition ↗
The Hoechst works also entered IG Farben in 1925 and emerged again after the war. Hoechst and Rhône-Poulenc combined into Aventis in 1999. Sanofi-Synthélabo acquired Aventis in 2004, creating a documented historical path into today’s Sanofi.
Explore Sanofi’s portfolio ↗IG Farben exploited forced labor at Auschwitz-Monowitz. The United States Holocaust Memorial Museum documents the company’s role in the camp system and Bayer’s history within the conglomerate.
It also records that Fritz ter Meer, convicted of war crimes, returned to Bayer’s supervisory board in 1956 and remained until 1964. Corporate reconstruction did not erase continuity in personnel.
USDA seed-market evidence, published 2023 ↗
In 2018, the U.S. Justice Department required approximately $9 billion in divestitures to BASF to address competition concerns in Bayer’s Monsanto acquisition. This records both the concentration risk and the use of public authority to require structural changes.
A campaign can focus on a seed variety, trait license, herbicide, purchasing contract, or local supplier network. Each has a distinct set of buyers, suppliers and alternatives.
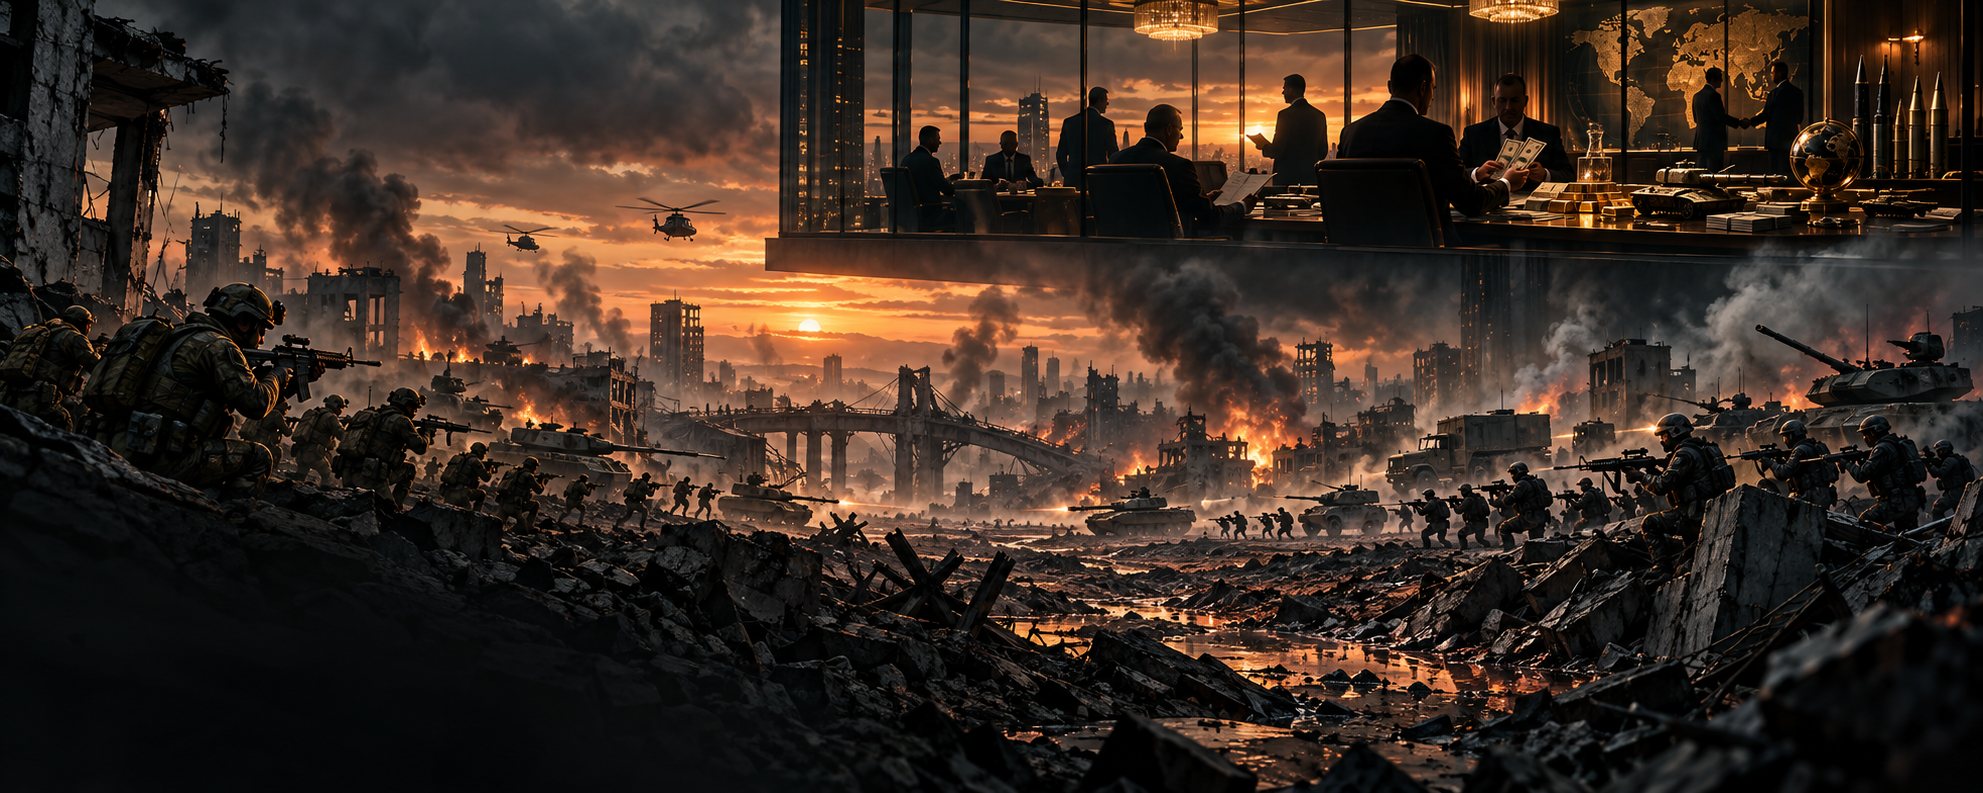
Industrial warfare could destroy societies while leaving particular suppliers, creditors and owners with larger earnings and lasting influence. Behind an army stand transport networks, steelworks, chemical plants, contracts and credit. Follow those institutions and war becomes an economic system as well as a military event: who supplies it, who finances it, who gains, and who carries the losses?
The Harriman–Bush story connects railroad capital, private banking and political succession. The wartime record then opens a wider inquiry into the arms trade, public procurement and corporate participation in Nazi rearmament and persecution.
E. H. Harriman helped consolidate a railroad system: his investor group acquired most Union Pacific assets in 1898; Union Pacific assumed control of Southern Pacific in 1901. His sons W. Averell and E. Roland Harriman carried the family's financial enterprise into the banking world. In 1931 the Harriman firms and Brown Brothers combined as Brown Brothers Harriman.
Union Pacific · corporate timeline ↗ · BBH · the 1931 merger ↗
Prescott Bush was a BBH partner before entering the U.S. Senate. He represented Connecticut from 1952 to 1963 and was the father of George H. W. Bush and grandfather of George W. Bush. Banking relationships and political family succession belong on the same historical map; responsibility for a particular act belongs to the people and institutions involved at that time.
BBH · Prescott Bush's banking career ↗ · U.S. Senate · Connecticut history ↗
Samuel Prescott Bush, Prescott Bush's father, led Buckeye Steel Casting Co. The April 1919 Federal Reserve Bulletin identifies him as a former director of the War Industries Board's Facilities Division and chief of its Forgings, Guns, Small Arms, and Ammunition Section. His career connects industrial management with the administration of wartime production.
Federal Reserve Bulletin · April 1919, p. 342 ↗ · Stevens · Bush family connection ↗
A July 1917 Treasury communication listed a Russian request for credits and cash that included $25 million for a Remington rifle contract and $15 million for Westinghouse rifles, alongside interest on borrowing. In March 1918, U.S. correspondence prioritized interest and other obligations over earmarking surplus Russian funds for a later Remington payment.
FRUS · credit request, 25 July 1917 ↗ · FRUS · payment priorities, 7 March 1918 ↗
The records reveal intersecting industrial, administrative and financial functions. The Remington figures describe requested financing, not approved disbursements or net profit. Samuel Bush's office and the company's contracts are separate documented connections; these records do not establish his ownership of Remington or personal control of those contracts.
Choose a trail to inspect its institutions and the relationship between them. Ownership, family succession, procurement and central-bank credit convey different powers.
Owned or controlled the Dutch bank
Rotterdam beneficiary
4,000 shares held for that beneficiary
The order identifies the beneficiary behind UBC's registered shareholders. It places E. Roland Harriman and Prescott Bush on that register; it does not quantify money passed to the Nazi regime. Read the actual instrument alongside the names.
Vesting Order 248 transferred all 4,000 UBC shares and specified creditor claims to the Alien Property Custodian. The register listed E. Roland Harriman: 3,991 shares and Prescott S. Bush: one. The order identified the Dutch bank as beneficiary of all the shares and Thyssen-family members as its owners or controllers.
This was an enemy-property action against UBC interests, rather than a seizure of BBH. It was not a criminal conviction of Bush. Registered holdings here cannot be read as each individual's beneficial wealth.
Machine guns, heavy artillery, submarines, aircraft and mechanized transport made military power increasingly dependent on specialized industry. More destructive equipment also created a market for replacement arsenals. The Nye Committee's 1936 report described sellers using fear of a potential enemy's purchases to stimulate new orders; it investigated bribery, foreign licensing, price arrangements and opposition to disarmament.
The resulting incentive is stark: a rival's new weapon becomes an argument for another purchase. Scientific advances could expand both destructive capacity and the commercial demand for keeping pace. This feedback loop is an interpretation of the committee's findings, rather than a claim that arms firms alone started the wars.
Nye Committee report · 1936, pp. 3–13 ↗
Finance also entered the supply chain. In April 1915, Lloyd George confirmed J. P. Morgan & Co.'s appointment as U.S. purchasing agents for British Admiralty and War Office requirements, with exceptions. The later Senate inquiry held 93 hearings and examined more than 200 witnesses, including Morgan Jr. and Pierre du Pont. It exposed munitions profits while finding little hard evidence for an active arms-makers' conspiracy to bring America into war.
Hansard · 20 April 1915 ↗ · U.S. Senate · the Nye investigation ↗
Nazi power rested on political dictatorship, ideology and coercion, supported by industrial production and financial administration. Business participation included funding, credit, dispossession, plunder and forced labor. These relationships can be examined through named transactions and judicial findings.
Evidence introduced at Nuremberg records IG Farben's 400,000 Reichsmark contribution to the February 1933 election fund. Hitler was already chancellor. The fund supported his governing coalition; it should be understood as financing consolidation of power.
Hjalmar Schacht used Mefo bills to finance rearmament through central-bank credit. Armament orders, manufacturers and Reichsbank liquidity formed an organized financing mechanism. A modern military required a financial infrastructure as well as factories.
Banks helped transfer Jewish-owned businesses under "Aryanization." Private firms participated in forced labor; IG Farben's factory complex near Auschwitz exploited prisoners in lethal conditions. These were forms of active participation in dispossession and mass suffering.
Fritz Thyssen supported the Nazi movement, joined the party in 1931 and helped connect Hitler with industrial leaders. He later broke with the regime, fled in 1939 and was arrested and interned. Industrial collaboration and coercive state power coexisted. The UBC record identifies Thyssen-family interests; it does not by itself measure their support to Hitler.
In the IG Farben case, 13 of 23 defendants were convicted for plunder and/or forced labor; all were acquitted on aggression and conspiracy counts. In the Krupp case, 11 of 12 were convicted for forced labor, with six also convicted for plunder; aggression and conspiracy counts were dismissed. The verdicts establish serious, specific corporate-leadership crimes. Those findings carry more precision than assigning a single generic "control" relationship to every company.
Ford's influence extended from factories into publishing. His Dearborn Independent ran the 1920–1922 articles collected as The International Jew, chiefly written by editor William J. Cameron and distributed in four volumes. Ford supplied the platform and promoted the material; the work was not simply a book he wrote alone.
The Henry Ford · original volume and publication history ↗
His distrust of financiers and modern cultural change became entangled with antisemitism. The publications falsely portrayed Jewish people as a collective hidden power behind banking, war and the press, drawing on the fabricated Protocols of the Elders of Zion. These claims turned criticism of economic institutions into ethnic scapegoating.
The exhibit reads this as another use of concentrated power: a wealthy industrialist's media platform gave false accusations an audience and the authority of his public reputation. A structural account follows ownership, contracts and decisions; Ford's propaganda substituted collective blame for those mechanisms.
The Henry Ford · historical analysis and archival references ↗
Ford's American factories became part of the Allied arsenal. At Willow Run in Michigan, workers produced 6,792 complete B-24 bombers and 1,893 assembly kits by June 1945. Public military orders mobilized the company's industrial capacity on an enormous scale.
The German subsidiary manufactured vehicles for Nazi Germany and exploited forced workers. Ford's own 2001 archival report places the first prisoners of war at its Cologne plant in September 1940; concentration-camp prisoners were used late in the war. Formal Nazi custodianship followed on 15 May 1942. Forced labor therefore preceded that administrative takeover.
Ford's 2001 report · forced labor, PDF pp. 74–75 ↗ · Custodianship, PDF pp. 58–59 ↗
Ownership, management and state control are different kinds of power. Ford retained an ownership interest while Nazi authorities imposed wartime control. The company-sponsored report is evidence to scrutinize alongside independent scholarship and the workers' experiences. These records support an inquiry into particular factories, decisions and responsibilities.
Ford signed a retraction in 1927, acknowledging the Protocols as forgeries and withdrawing collective accusations. His statement also claimed he had been unaware of the publications' content; that was his explanation, rather than an independent finding.
Hitler admired Ford, and Nazi Germany awarded him the Grand Cross of the German Eagle in 1938. The history connects industrial reputation, publishing influence and ideological admiration; each connection needs its own evidence.
AJC archive · Ford's 1927 statement ↗ · German Historical Institute · the Ford–Nazi connection, pp. 143–144 ↗ · USHMM · Ford's propaganda and wartime production ↗
Destruction leaves an urgent need for food, fuel, machinery and transport. Reconstruction creates orders for suppliers and a need for financing. The terms decide who supplies the goods, who receives fees or interest, and which obligations remain with the rebuilding society. Relief, recovery and commercial opportunity can exist within the same program.
The 1924 Dawes Plan included a $200 million stabilization loan floated by J. P. Morgan on the American market. Further U.S. lending helped Germany pay reparations; France and Britain used those receipts to service their war debts to the United States. Private lending and public debt payments became interdependent.
The Young Plan proposed another $300 million loan. The Depression and the drying-up of American credit exposed the circuit's fragility. These were Weimar-era arrangements, preceding Nazi rule.
U.S. State Department · Dawes, Young, and inter-allied debts ↗
The Bank for International Settlements, established in 1930 in connection with the Young Plan, supplied institutional machinery for reparations and acted as agent or trustee for the Dawes and Young loans. An international settlement institution and a private lending bank perform different roles.
BIS · foundation and financial-settlement role ↗
The World Bank's first loan went to France's Crédit National, guaranteed by the French Republic. Signed on 9 May 1947, it financed imported equipment, fuel and materials. The 30-year agreement charged 3¼% interest plus a 1% annual commission on the outstanding balance; principal repayments were deferred for five years.
The Bank required documentation of purchases and their use. Credit thus came with repayment obligations and supervision of expenditure.
Original 1947 announcement and loan terms ↗ · World Bank · digitized negotiation and administration records ↗
Congress appropriated about $13.3 billion for European recovery over four years. More than 90% of the European Recovery Program took the form of grants; a smaller portion was lending. It restored productive capacity while creating markets for American goods and supporting U.S. strategic aims.
A grant did not impose the same principal-and-interest obligation as a loan. The mix of instruments matters when assessing who paid and who benefited.
National Archives · recovery, trade and strategy ↗ · Congressional Research Service · grants and loans, p. 10 ↗
Business careers also entered reconstruction administration. The Congressional Research Service identifies Studebaker president Paul G. Hoffman as the European Recovery Program's administrator and Averell Harriman as head of its Paris regional office, serving as U.S. Special Representative Abroad. This connects the Harriman story to the administration of postwar recovery through a documented public appointment.
CRS · Hoffman, Harriman and recovery administration, p. 10 ↗
The exhibition's synthesis follows the movement from wartime procurement to postwar rebuilding: weapons and supplies during conflict; equipment, materials and finance afterward. Specific firms and creditors could benefit at either stage. Establishing that one actor deliberately engineered both requires transaction and decision records beyond the existence of these markets.
The U.S. Commerce Department's April 1946 assessment shows how wartime production strengthened aggregate corporate earnings. The comparison below uses its contemporary estimates of annual profits after corporate taxes, in nominal dollars.
Retained corporate earnings totaled about $25 billion in 1941–1945, furnishing resources for postwar expansion. Taxes also absorbed a much larger portion of profits; the report notes that excess-profits taxation held after-tax profit margins below their 1929 level. These are economy-wide corporate figures, rather than a weapons-company total or a measure of every financier's gain.
Commerce · Survey of Current Business, April 1946, pp. 9–10 ↗
Outcomes differed. BBH's own history reports that Germany's 1931 debt standstill froze over $10 million of its credits and required an emergency Harriman capital infusion. A serious account of economic winners must follow losses and state protection alongside earnings.
BBH's institutional account · the standstill crisis ↗
The exhibition's argument is that war can concentrate capital and institutional power even while destroying the lives and wealth of millions. The records show identifiable beneficiaries and mechanisms. They do not make every firm a winner or reduce the causes of either world war to profit alone. Revenue, net profit, political influence and criminal complicity each require their own evidence.
The Truman Committee investigated wartime waste and conflicts involving government executives still paid by corporations. In 1961 Eisenhower warned about the influence of a permanent arms industry joined to a large military establishment and costly, government-directed research. The question extends beyond a single war: when procurement becomes permanent, who shapes the demand?
U.S. Senate · the Truman investigation ↗ · National Archives · Eisenhower's farewell address ↗
Follow the public budget, the purchasing contract, the supplier and its owners. Then examine lobbying, appointment powers, oversight and the terms of renewal. The boycott histories that follow ask how organized people can redirect support and exert pressure on institutions with specific powers.
Historical sources reviewed October 2026. Government records, parliamentary proceedings, trial evidence, museum scholarship and institutional histories are identified beside the claims. The relationship viewer is a selected historical model, not a complete map of wartime finance.
Continue: refusal has a history ↓The most durable campaigns paired withdrawal with organization, practical alternatives, and demands that could be met.
Organized refusal of British imports helped turn consumption into political action. Most Townshend duties were repealed in 1770; the duty on tea remained. Multiple pressures shaped the outcome.
Library of Congress ↗The destruction of East India Company tea was distinct from a purchasing boycott. Parliament retaliated, including closing Boston's port. Symbolic disruption can mobilize a movement and impose costs on participants.
National Park Service ↗Participants refused segregated buses while an organized carpool helped people reach work. A parallel court challenge struck down bus segregation. Alternative transportation made sustained withdrawal possible.
National Park Service ↗Farmworkers combined strikes, boycotts, marches, and organizing. Collective bargaining agreements followed in 1970. Consumer solidarity strengthened a campaign led by workers.
National Park Service ↗Campaigns carried economic pressure into universities and institutional investment portfolios. In 1987, Smithsonian regents voted to divest $32 million in holdings in companies operating in South Africa. The decision carried organized public pressure into an institution’s investment policy.
Specific demands. Trusted organizers. Practical support for participants. Sustained public visibility. Review dates and a credible way to recognize concessions. The goal is to make a change in conduct more attractive than continued resistance.
Ask workers and affected communities what support they need. A campaign can hurt frontline employees or independent retailers before it changes executive decisions. Mutual aid and clear targeting help keep participation sustainable.
A familiar restaurant sign can connect to an operating group, an investment firm and a local franchise business. Trace each layer. This research adds 46 restaurant entries across 17 groups, with completed deals, former investments and territorial rights kept visible.
The franchisor holds the brand and franchise relationships. Several restaurant names can share that parent.
A private-equity sponsor can invest across several operating groups. A majority acquisition and a minority stake convey different powers.
Franchisees may own local businesses while paying royalties and other fees to the brand system. Trace the local operator alongside the parent.
LongRange Capital acquired the business outside Mainland China on September 1, 2026. The separate Mainland-China transaction with Yum China closed August 7. Yum's current portfolio lists KFC, Taco Bell and Habit. The map records both Pizza Hut territories separately.
Select a brand to inspect its path in the ownership atlas. Use "Compare brands" to reveal shared investment sponsors and ended ownership connections. Logos and site icons aid identification; the linked records establish the relationship. Initials appear when an image is unavailable.
| Date | Connection | Relationship / evidence |
|---|
Inspire announced a confidential registration submission in May 2026. The cited announcement describes a proposed offering.
Company announcement ↗The September 2026 update proposed a Hong Kong listing for the international business. The existing group remains mapped while the proposal awaits completion.
Company announcement ↗Restaurant records reviewed October 17, 2026. Other atlas entries retain their own review dates. Selected relationships; individual restaurant ownership and local franchise arrangements can vary.

A different label can lead back to the same company. Explore the connections before deciding where to direct your spending.
Selected portfolios span food, household goods, healthcare, agriculture, finance, energy, defense, news and digital platforms. Counts refer to mapped entries; a shared product can appear under more than one commercial partner.
Select a brand node to inspect its connection. The diagram adapts to your screen; Text view provides a compact list.
Compare two names before redirecting your spending. A change of brand may leave the parent company unchanged.
Compare parent companies, commercial ties and voting structures. Product rights and availability vary by country. A clinician or pharmacist can advise on the suitability of treatment alternatives.
Corteva completed the separation of its seed business into independent Vylor on October 1, 2026. Pioneer, Brevant, and other selected seed brands are mapped to Vylor. Crop-protection products remain in the Corteva record.
J&J’s former consumer-health business separated in 2023; J&J disposed of its remaining Kenvue shares in May 2024. Kenvue became the corporate home of the separated consumer-health portfolio.
Mars completed its Kellanova acquisition on December 11, 2025. Pringles, Cheez-It, Pop-Tarts, Rice Krispies Treats, and RXBAR are mapped through Kellanova to Mars.
Completion announcement ↗Magnum became a separate listed company in December 2025. Unilever’s June 2026 filing records a retained 19.85% equity stake. That minority interest is distinct from control of the whole company.
Dated ownership record ↗Unilever’s Foods combination with McCormick remains a proposed transaction in the reviewed record, with completion expected by mid-2027 subject to conditions.
Transaction status ↗Solid branches show recorded portfolio or corporate relationships; dashed copper branches identify shared commercial products. “Via” labels name intermediate businesses. Select a node for its relationship type, territorial scope and shared-rights details.
Shareholders sit above the corporate-parent layer. Selected control records identify voting blocks, enhanced share rights and board-election powers. Asset managers may vote shares held for fund investors; the fund mandate and proxy record show how those rights are exercised.
FTC staff’s January 2025 interim report examined specialty generic drugs dispensed during 2017–2022. It found over $7.3 billion in dispensing revenue above estimated acquisition costs at pharmacies affiliated with the three largest PBMs. The estimate describes a dispensing spread before other expenses in that specialty-generic sample.
Millions of people supply the savings. A much smaller set of institutions manages the portfolios, casts delegated votes, arranges acquisitions, and operates the systems through which the money moves.
Behind the brands in the ownership atlas sits another network. BlackRock, Vanguard and State Street are central to it, alongside private-capital firms, insurers, banks, index providers and technology platforms. Explore who is connected, what kind of authority each relationship creates, and where the money changes hands.
Assets under management
2025 financial results ↗Assets under management
Vanguard overview, p. 5 ↗Assets under management
2025 financial results ↗State Street also reported assets under custody and/or administration at year-end 2025. This is a servicing measure. The same securities can be managed by one firm and serviced by another. State Street’s AUM includes about $173 billion for which an affiliate acts solely as marketing agent. Read the definitions ↗
The power question is about authority as well as wealth. AUM measures assets managed for clients. It does not measure a manager’s own fortune. Economic risk, investment decisions, voting rights and custody can sit with different people and institutions. The map keeps those relationships distinct.
Select a layer, choose an institution, then tap a connected node to follow the network. Select a line or a connection in the list to inspect its date, source and limits. Arrowheads run from the named actor to the recipient of the relationship; line widths do not represent dollars.
Drag the horizontal scrollbar on small screens · Focus map shows the selected institution’s direct documented connections
These pathways explain mechanisms. They are illustrative arrangements, not audited transaction totals. Select a route, then a stage, to see where economic ownership, fees and authority can diverge.
A stock purchase has two different money routes. In a primary issuance, new capital reaches the issuer. In a secondary-market trade, the buyer pays the selling investor. A fund appearing on a shareholder list does not mean the company receives that purchase price.
SEC: primary market ↗ · SEC: secondary market ↗BlackRock’s 2024 reconciliation separates new client flows, acquired mandates, market movements and currency effects. The bars show the relative size of each annual change. They are not a map of cash taken from the public.
BlackRock Q4 2024 results, AUM reconciliation ↗
Positive and negative changes use a common magnitude scale. Rounded totals; individual components shown in billions.
Net subscriptions and withdrawals change the pool entrusted to a manager. Those clients may include pensions, institutions and households; AUM alone does not identify who benefited.
An acquisition can move an investment-management business under a new corporate parent while the underlying fund investors retain their economic interests.
Stocks and bonds can become more valuable without an equivalent new cash payment to the manager. Market gains are different from acquisition-driven concentration.
Fund and service fees can transfer income to financial businesses. The value of the portfolios is a separate measure from that income.
Corporate acquisitions transfer business ownership. Asset purchases can transfer selected operations and deposits. Service contracts and fund mandates create a different kind of dependence. Dates below refer to completion unless a record explicitly says otherwise.
Investors own fund shares; funds hold securities. Vanguard’s member funds own the management company. BlackRock and State Street have publicly traded parent companies. Putting all three into a reciprocal corporate-ownership triangle would misstate that structure.
Vanguard ownership ↗Investment discretion, beneficial-ownership reporting and voting authority can differ. A Form 13F position is not a complete record of votes. Check proxy footnotes, Schedule 13D/13G disclosures and fund voting reports before claiming how a manager exercised power.
SEC Form 13F FAQ ↗A new proxy can reuse an older ownership filing. The historical portfolio links in this chapter retain their underlying dates. Vanguard’s January 2026 reorganization also changed reporting entities; an apparent disappearance from a database need not mean the underlying securities were sold.
Vanguard SEC supplement ↗Funds can hold stakes in competing companies. Whether that overlap weakens competition depends on incentives, governance and observed conduct. Airline studies reach differing results under different models. Shared holdings alone do not establish collusion or operating control.
2018 airline study ↗ · 2022 reanalysis ↗A manager can depend on Aladdin, a cloud provider, an index license, or a custodian without transferring every investment decision to that supplier. Switching costs and service dependence are questions to investigate separately from shareholder control.
Microsoft Treasury case study ↗Voting-choice programs let some clients or fund investors select voting policies. Eligible assets, participating assets and votes actually directed are different measures. Check the mandate and participation data before drawing one institution as a single uniform voting bloc.
Vanguard 2025 participation report ↗Exhibition interpretation: Financial power can concentrate at several points at once: the collection of capital, investment decisions, voting, credit, ownership of businesses and operational infrastructure. This map documents selected relationships. The consequences must be tested against actual conduct, benefits, costs and alternatives.
Identify savers, policyholders, pensions, public institutions and other ultimate beneficiaries. Ask who bears losses and who receives the returns.
Identify the mandate: votes, board rights, lending covenants, a controlling acquisition, or a service agreement. Look for evidence that the authority was used.
Trace management fees, interest, transaction fees, carried interest and dividends. Separate payments for services from changes in asset value.
Return to the corporate ownership atlas ↑ · Connect the research to collective action →
Every mapped connection links to a dated primary record.
Download the complete financial evidence file ↗
Coverage: selected financial institutions and documented relationships, assembled from “Map Financial Power” and independently checked primary records. Reviewed October 10, 2026. Metrics use an explicit year-end 2025 snapshot; transaction and filing dates vary. Historical links are retained to explain development. The map is not a complete or synchronized census of portfolios, beneficial owners, cash flows or every subsidiary.
Insurance sits where money, treatment and permission meet. Networks determine which providers are accessible. Benefit rules shape what is covered. Authorization decisions can turn a clinical recommendation into a negotiation over payment.
Premiums, plan-administration fees and public-program payments.
Networks · benefits · claims · prior authorization
Payments to providers and pharmacies; administration and margin within the financing model.
Conceptual flow. In an integrated group, affiliated pharmacies and care providers can receive payments within the same corporate family.
Humana’s CenterWell segment recorded $17.7 billion from transactions with other Humana segments and $4.8 billion from external customers in 2025. Pharmacy, primary care and home health sit alongside the insurance business.
Intersegment transactions are eliminated in consolidated accounts. The figures show internal financial flows.
Medicaid managed-care organizations receive fixed monthly payments per enrollee from state agencies. Medicare Advantage also channels public financing through private plans.
MedPAC projected $615 billion in Medicare Advantage payments in 2026, including an estimated $76 billion above spending for comparable beneficiaries in traditional Medicare. These program payments cover care, supplemental benefits, administration and margins.
CMS Medicaid managed care ↗ · MedPAC March 2026 Medicare Advantage status report ↗
HHS OIG skilled-nursing prior-authorization review ↗
| Corporate group | Insurance, administration & care businesses |
|---|---|
| UnitedHealth Group ↗ | UnitedHealthcare → insurance · Optum → health services |
| CVS Health ↗ | Aetna → insurance · CVS Caremark → PBM · CVS Pharmacy → dispensing |
| The Cigna Group ↗ | Cigna Healthcare → insurance · Evernorth → Express Scripts / Accredo |
| Elevance Health ↗ | Anthem / Wellpoint → health plans · Carelon → pharmacy and care services |
| Humana ↗ | Humana → insurance · CenterWell → pharmacy, primary care and home health |
| Centene ↗ | Ambetter → Marketplace · Wellcare → Medicare · local plans → Medicaid |
| Health Care Service Corporation ↗ | State BCBS plans · HealthSpring → Medicare · CareAllies / Luminare → services |
Elevance’s June 2026 filing says CarelonRx delegates certain core pharmacy services to CVS subsidiary CaremarkPCS under an agreement extending through December 31, 2027. Ownership is one layer of the system; service contracts create another.
Commercial medical-loss-ratio rules generally require 80% of individual and small-group premiums, or 85% of large-group premiums, to fund medical care and quality improvement, with rebates for shortfalls. The remainder supports administration and profit under the applicable calculation. Self-funded employer plans follow a different framework.
For an integrated group, examine insurance results together with the costs and revenues of its pharmacy and provider businesses. A useful financial model identifies which entity receives each payment and what expenses it must cover.
CMS commercial medical-loss-ratio rules ↗ · CMS MLR technical guidance, April 20 2012 ↗
Senior careers connect corporate management, public oversight and industry advocacy. Policy knowledge and professional networks travel with those appointments. Accountability begins with a dated record of roles, financial interests, recusals and decisions.
Optum → CMS
Optum’s former group executive vice president joined CMS in 2014 and later became acting administrator.
Appointment record ↗ · Congressional record ↗CMS → AHIP
After leaving CMS in February 2015, Tavenner was elected president and CEO of America’s Health Insurance Plans on July 15, 2015.
Appointment record ↗FDA → Pfizer board
After serving as FDA commissioner from 2017 to 2019, Gottlieb joined Pfizer’s board on June 27, 2019, including its regulatory-and-compliance and science-and-technology committees.
Appointment record ↗Appointment records establish the career path; policy and enforcement records show how public authority was exercised.
Pfizer, Moderna and other drugmakers develop and market products through research, acquisitions and licensing. Patents and FDA marketing exclusivity provide different forms of protection and can overlap.
Pfizer and BioNTech collaborate on Comirnaty; Lilly and Boehringer Ingelheim collaborate on Jardiance. Shared commercial rights appear as dashed connections in the atlas.
FDA: patents and exclusivity ↗Employers, unions and public agencies purchase coverage at scale. Collective demands can focus on denial and appeal data, pharmacy-contract transparency, adequate provider networks and independent review.
CMS requires specified payers to publish annual prior-authorization metrics for covered medical items and services. That public record gives organizers a starting point for comparing access.
CMS prior-authorization reporting requirements, updated September21 2026 ↗
A subscription pays a publisher. A viewing habit attracts advertisers. A feed gives a platform information about what holds your attention. Follow all three, and a daily routine becomes a map of economic support.
Reporting and programming are produced, commissioned and licensed.
Carriage, recommendations and rankings shape which material reaches an audience.
Subscriptions, advertising, distribution fees and licensing send value back through the system.
A conceptual model of production, distribution and revenue. Specific ownership and control records follow.
Start with a familiar outlet, follow its corporate parent, then examine the voting structure above it. Each property card opens the same sourced atlas used for food, healthcare and other industries.
CBS News · CNN · Paramount+ · HBO Max
FOX News · FOX Business · FOX Nation · Tubi
The Wall Street Journal · Barron’s · MarketWatch · New York Post
ABC · ABC News · ESPN
NBC News · Telemundo · Peacock · Sky
MS NOW · CNBC · USA Network · E!
The New York Times · The Athletic · Wirecutter · NYT Games
Reuters · Reuters Connect
The Washington Post
Paramount completed its acquisition of Warner Bros. Discovery on October 6, 2026; the combined company, Skydance, contains CBS News and CNN. Versant became independent of Comcast on January 2, 2026 and houses MS NOW and CNBC. NBC News remains within NBCUniversal/Comcast; the proposed NBCUniversal/Sky separation is expected around June 2027, subject to conditions.
Skydance closing ↗ · Versant separation ↗ · Comcast proposal ↗
A public listing can coexist with concentrated decision-making rights. These records distinguish a shareholding from voting power and the power to elect directors.
| Company | Holder & mechanism | Documented rights |
|---|---|---|
| Skydance ↗ | Ellison family + RedBird Voting Class A stock | Together hold 100% of voting shares of the combined company. As of 2026-10-06 · Record ↗ |
| Fox Corporation ↗ | LGC Holdco / Cruden 2 Class B voting block | 38.76% of Class B; votes generally directed by the Cruden 2 director appointed by Lachlan Murdoch. As of 2026-09-14 · Record ↗ |
| News Corp ↗ | LGC Holdco / Cruden 2 Class B voting block | 34.8% of Class B; votes generally directed by the Cruden 2 director appointed by Lachlan Murdoch. As of 2026-08-28 · Record ↗ |
| Comcast ↗ | Brian L. Roberts Enhanced Class B voting rights | Generally non-dilutable 33⅓% of combined voting power. As of 2026-04-08 · Record ↗ |
| Versant Media Group ↗ | Brian L. Roberts Enhanced Class B voting rights | Generally non-dilutable 33⅓% of combined voting power. As of 2026-04-14 · Record ↗ |
| The New York Times Company ↗ | Ochs-Sulzberger Family Trust Board-election rights | Approximately 95% of Class B shares; ability to elect 70% of directors. As of 2025-12-31 · Record ↗ |
| Thomson Reuters ↗ | Woodbridge / Thomson family Majority common-share ownership | Approximately 71% of common shares. As of 2026-04-13 · Record ↗ |
| Nash Holdings / Jeff Bezos ↗ | Jeff Bezos Private ownership | The Washington Post is personally held through Nash Holdings. As of 2026-10-08 · Record ↗ |
| Meta Platforms ↗ | Mark Zuckerberg Majority voting power | Voting control over matters submitted to shareholders, including director elections. As of 2026-06-30 · Record ↗ |
Fox and News Corp share a Murdoch-family voting structure through LGC Holdco. Comcast and Versant both give Brian Roberts enhanced voting rights. These are named connections across distinct corporate groups.
YouTube · Google Search · Google Ad Manager
Google Services combines search, video, advertising tools and subscriptions. YouTube earns advertising and subscription revenue and pays content providers through licensing and revenue arrangements.
Open platform map ↗Facebook · Instagram · Messenger · WhatsApp
Meta’s Family of Apps includes Facebook, Instagram, Messenger and WhatsApp. Its June 2026 filing describes Mark Zuckerberg’s majority voting power and consequent control over matters submitted to shareholders.
Open platform map ↗Prime Video · Twitch · Amazon Ads
Amazon connects retail, video subscriptions, livestreaming and advertising. Its advertising business sells sponsored, display and video placements; its media services also earn subscription and content revenue.
Open platform map ↗FTC staff’s 2024 study documented extensive data collection and business incentives to monetize personal information through targeted advertising. FTC research ↗
| Layer | Connection to examine | Record to seek |
|---|---|---|
| Governance | Voting rights, director appointments, ownership trusts | Proxy statements, annual filings, trust and share-class disclosures |
| Finance | Advertising, subscriptions, distribution and licensing | Revenue disclosures, carriage agreements, sponsorship labels |
| Distribution | Search rankings, recommendations, syndication | Platform policies, licensing terms and referral data |
| Professional networks | Board memberships and careers across companies or public institutions | Dated biographies, appointment records and conflict disclosures |
| Editorial decisions | Commissioning, corrections, staffing and newsroom policy | Published policies and documented decisions concerning a specific story or institution |
Ownership gives the investigation its structure. Editorial influence is evaluated through documented decisions, budgets and policies; a source’s reporting can then be judged on its evidence.
Economic agency grows through coordination. Shared research, collective purchasing and support for alternative institutions turn individual habits into sustained pressure alongside civic organizing.
Estimate how much participating retail spending moves outside a selected corporate group.
Assumes constant spending and average participation over the period. No automatic inference about corporate viability.
For 1,000 people redirecting $100 per month for six months, 70% average participation and 20% returning to the same parent produce $336,000 in modeled outside-parent spending. If 60% returns to that parent, the result falls to $168,000. Ownership research changes the scenario even when the number of participants stays the same.
Retail spending includes distributors, retailers and taxes. Translating it into a manufacturer’s revenue or profit requires additional data. Reputational effects, worker organizing, legal action and institutional procurement sit outside this calculation.
Track participation estimates and documented spending changes alongside company-wide sales. Assess results against other changes in demand, pricing and market conditions.

A boycott needs a shared plan. Teach people who receives their money, identify a change the target can make, and prepare alternatives before asking people to participate.
Use a documented practice and a responsible organization. Preserve dates, scope, and the organization's response.
Choose an observable change: transparent contract terms, a published appeals standard, or a verifiable policy revision.
Find genuinely separate suppliers and workable services. Account for price, distance, disability, employment, and essential needs.
Set a start date, a review date, a clear demand, and a small set of shared materials. Track participation and redirected spending without collecting unnecessary personal data. Keep participants informed about progress and changes.
State what ends the boycott. Verify implementation, acknowledge concessions, and revise the campaign when evidence changes.
Build participation around continuity of care and coverage. Support appeals, document access barriers and press plan sponsors for enforceable contract changes. Discuss treatment alternatives with a clinician or pharmacist. Direct primary care and cash payment leave major medical costs to be covered separately.
Canceling Marketplace coverage can leave someone unable to re-enroll until open enrollment unless they qualify for special enrollment. Preserve effective coverage while exploring changes; a sustainable campaign protects participants from avoidable medical and financial harm.
Save the source, date, affected market, responsible entity, and any response. Distinguish an allegation from a finding.
Specify who can act and what they should publish, revise, or stop. Choose a review date.
Check the parent, affordability, transport, accessibility, and supply capacity. Offer options for people who cannot switch.
Report participation honestly, correct ownership errors, document concessions, and explain when the campaign ends.
Example demand structure: “By [date], [decision-maker] will publish [specific information] and implement [verifiable change]. We will review progress using [named evidence].”
Ownership facts establish a relationship. Research findings have a defined sample and method. Allegations require attribution. Interpretations are arguments to examine. Scenarios are calculations under assumptions. These categories should remain visible as this exhibition grows.
Insurance, media & ownership edition • October 8, 2026 • Sources accompany claims and every corporate family. Ownership records are a dated snapshot; portfolios and proposed transactions require rechecking before campaign decisions.
Current portfolio: an association reported by a company or filing. Medicine listings may include licensing or commercial partnerships.
Historical succession: a dated merger, breakup or acquisition, recorded with the entities and assets involved.
Market concentration: a measured share in a named product, territory and time period, with the denominator and source attached.
Accountability: a specific practice or finding, evaluated through its evidence, affected communities and responsible decision-makers.
Company sources establish what firms say about their structure and portfolios; regulatory records and independent historical institutions support competition and historical claims. The downloadable JSON preserves sources, relationship types, historical transactions, voting-control records and dated career moves.